

The Opportunity
WHAT ARE PEPTIDES?
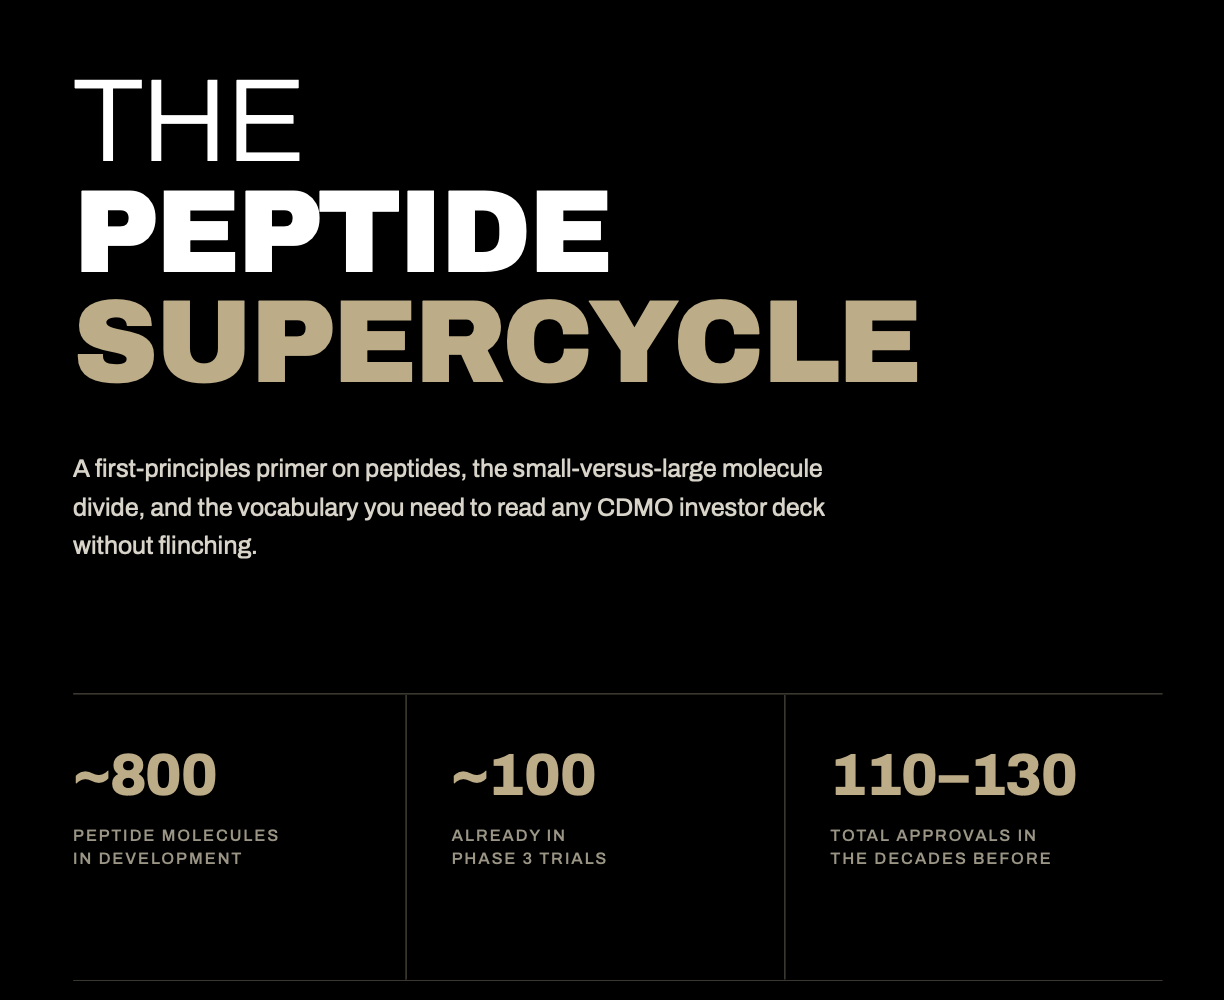
It took decades for roughly 110–130 peptide drugs to reach FDA approval. Today, nearly 800 are already in development. That single comparison tells you everything about where this industry is heading.
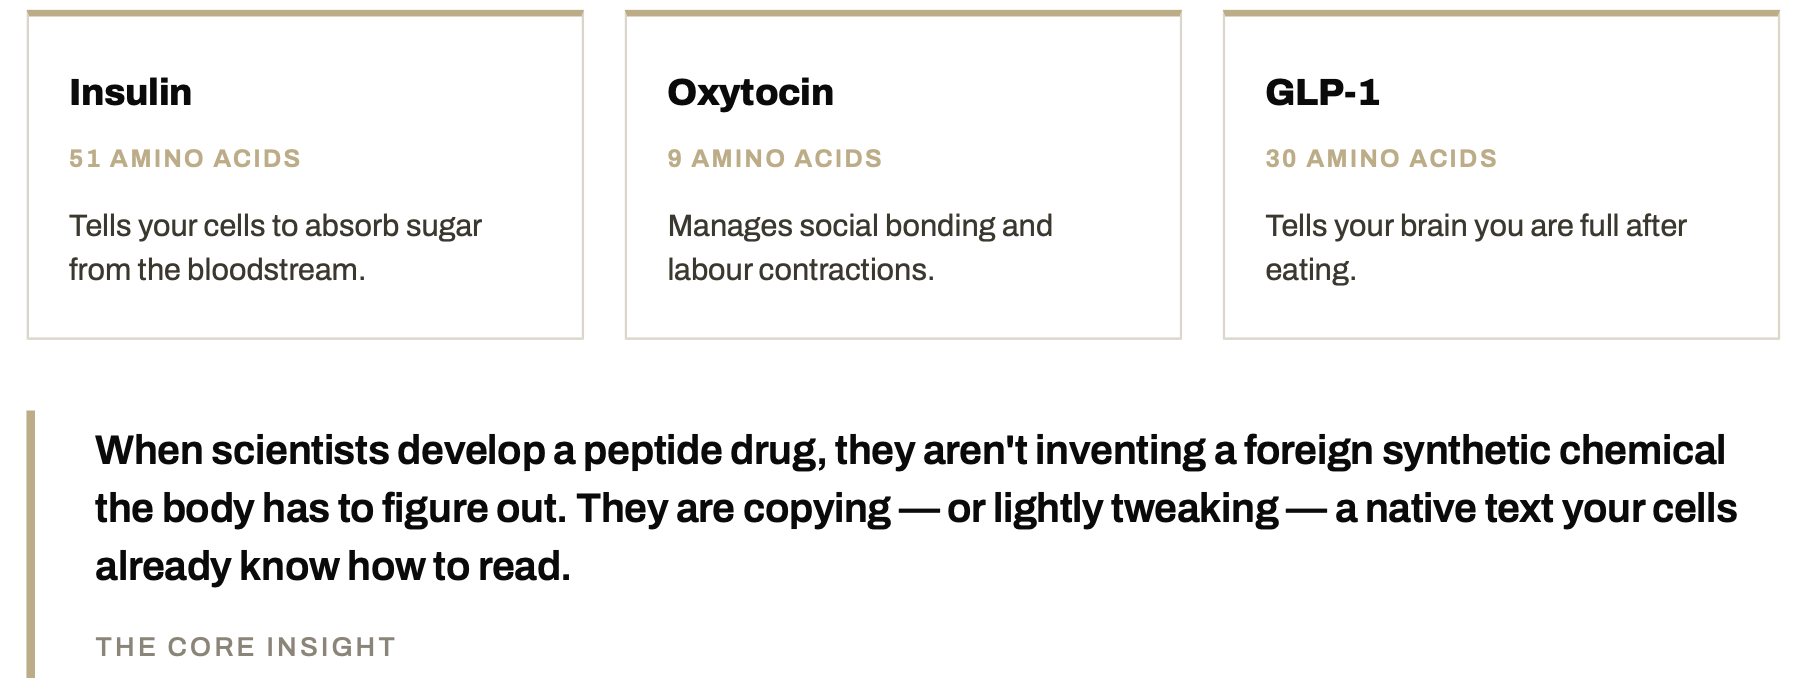
A peptide is a short chain of two to fifty amino acids linked by chemical bonds. Because amino acids are the building blocks of proteins, peptides are essentially mini-proteins which are tiny messengers that travel through the body telling cells what to do.
Your body already runs on them. Native peptides are the messaging system your cells use to control processes that happen every day, without you thinking about them
So why now, if peptides have existed for decades?
Because the science was never the bottleneck but manufacturing was. Peptide drugs were historically difficult and expensive to make at commercial scale: low yields, persistent impurity problems, and production processes that were complex enough to make large-volume economics unworkable.
That constraint has now been broken. Advances in solid-phase peptide synthesis (SPPS), automation, purification technology and process engineering have substantially improved manufacturing efficiency, product quality and scalability. What was once a specialty capability is becoming an industrial one and large-scale commercialisation is now genuinely feasible.
Layer on the commercial success of GLP-1 / GIP therapies and you have both halves of a supercycle: proven blockbuster demand meeting newly-viable supply economics.
The pipeline is deeper than it has ever been
Roughly 800 peptide molecules are under development globally. The ~100 sitting in Phase 3 matter most to a manufacturer: these are the molecules that will need commercial-scale capacity within a few years, and that capacity has to be booked long before approval.
Interest is broadening well beyond obesity into metabolic, cardiovascular, oncology and rare-disease indications. A pipeline that wide, converting over a decade, means demand for peptide manufacturing capacity should stay robust for years rather than quarters.
B O T T O M L I N E
Indian CDMO companies with peptide capacity are sitting in the middle of supercycle. Now go look for those.
The screening question is simple: who has commissioned peptide capacity, who has customers contracted against it, and who is still writing press releases about intentions? Capacity without contracts is just expensive steel — that distinction is where the returns live.
The Divide
SMALL VS LARGE MOLECULES
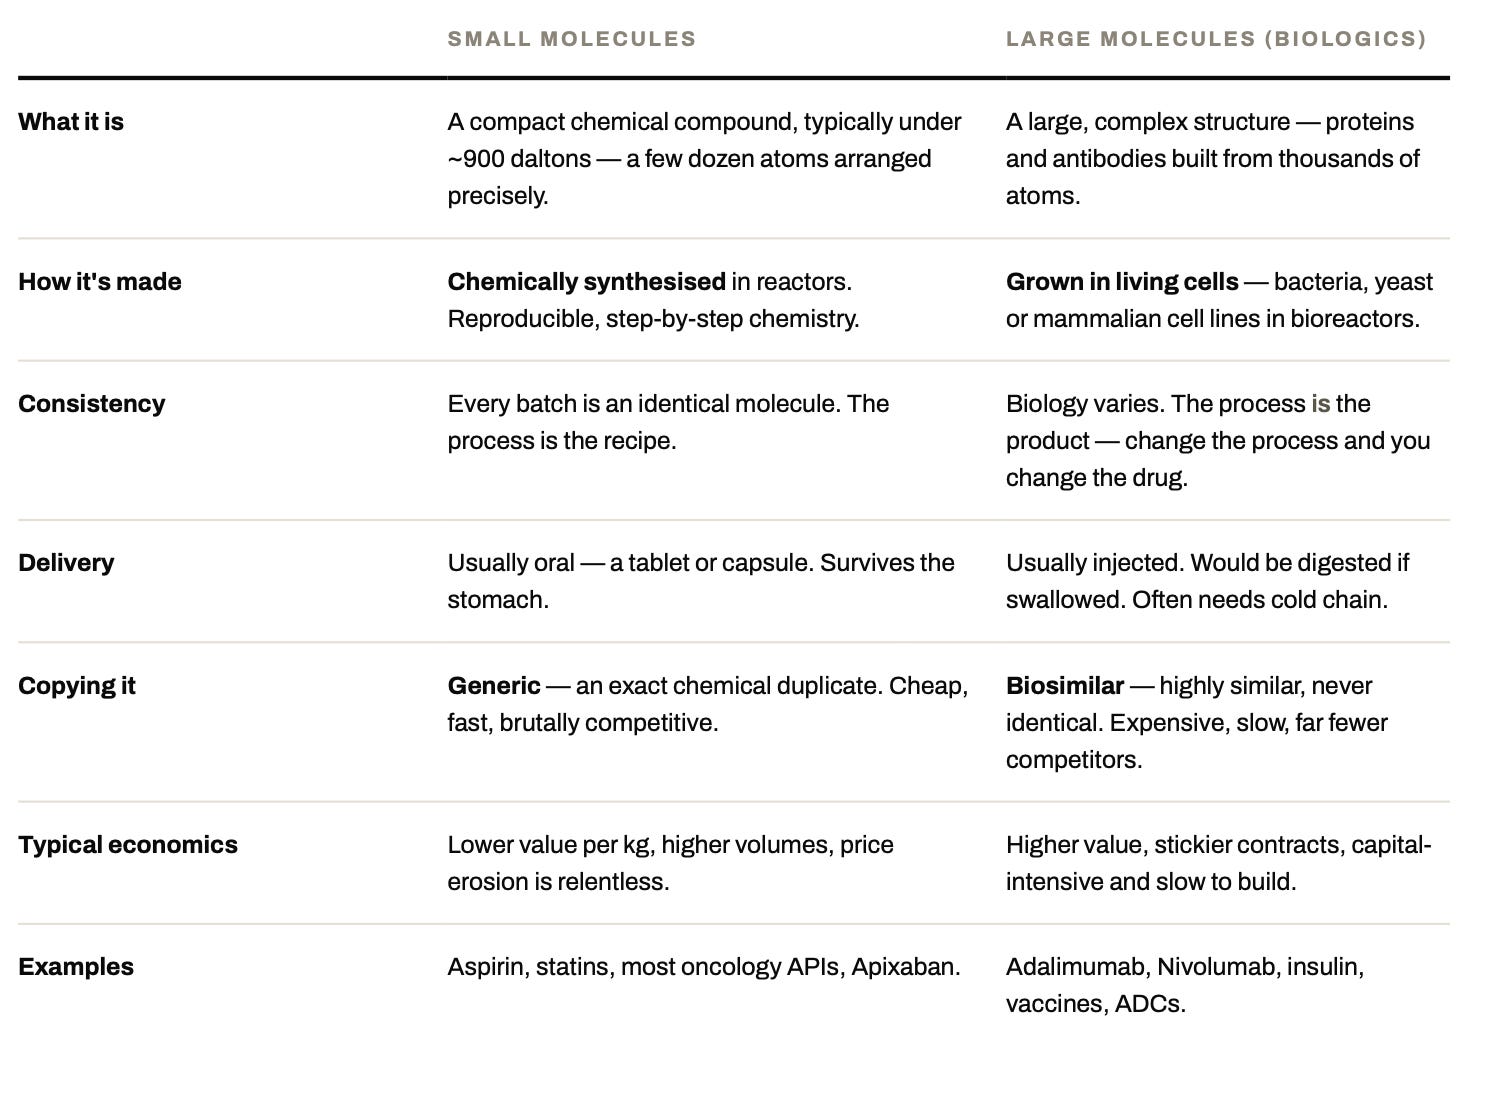
Almost every capability slide in a CDMO deck sorts itself along this one axis. Get it right and the rest of the deck decodes itself.
The difference is exactly what it sounds like, size but size drives everything else: how the drug is made, how it is delivered, how easily it can be copied, and therefore how durable the manufacturer’s economics are.
Where peptides sit and why that matters
Peptides occupy the middle ground, and that position is the whole investment story. They are chemically synthesised like small molecules (via SPPS, in reactors, not cell lines) but they are large and complex like biologics which are too big to simply swallow, difficult to purify, and demanding real technical skill to make at scale.
That combination is commercially attractive: a manufacturer gets biologic-like complexity and pricing power, without the full capital burden and regulatory drag of a mammalian cell-culture facility. It is also why “we have peptide capability” has quietly become the most repeated line in Indian CDMO investor decks and why it deserves scrutiny rather than applause.
Complexity is the moat. Anything a competitor can make easily, they will make cheaply and your margin goes with it.
When a company says “small molecule CDMO”, think chemistry, reactors measured in kilolitres, and API supply. When it says “large molecule” or “biologics”, think bioreactors measured in litres, cold chain, and much longer qualification timelines. When it says “peptides” or “TIDES” (peptides + oligonucleotides), think SPPS blocks and then ask the only question that matters: is that capacity contracted, or merely commissioned?
Decoding Peptide Capabilities
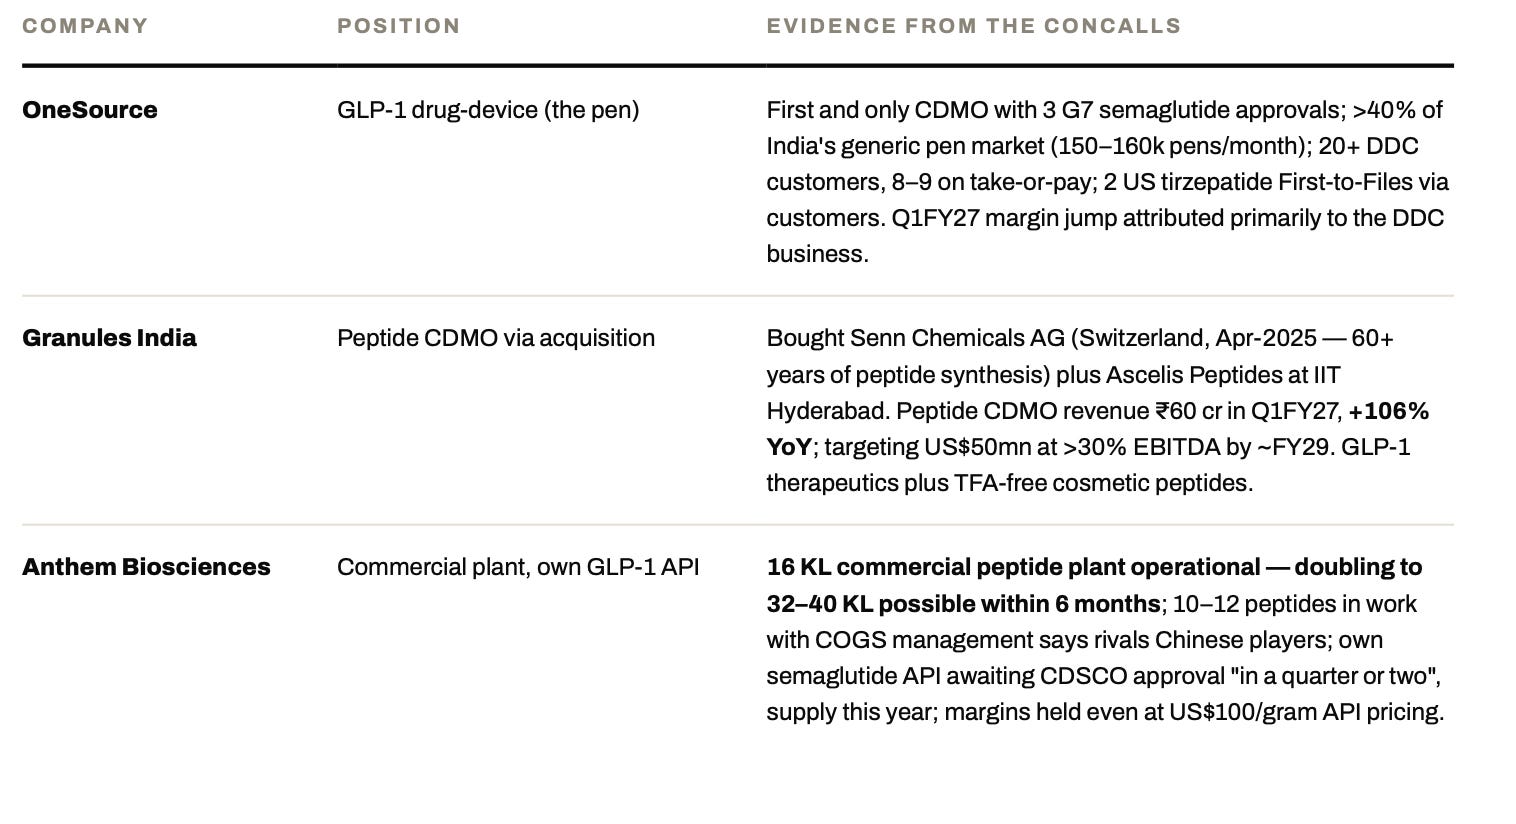
Every company on the SOIC CDMO tier map, placed on a five-rung readiness ladder is built from each company’s own Q1FY27 concall and disclosures. The discipline: a commissioned block with contracted volumes is a different asset from an announced intention, and an announced intention is different from silence.
Rung 1 — Earning peptide revenue today
Rung 2 — Contracted or commissioning inside 12 months
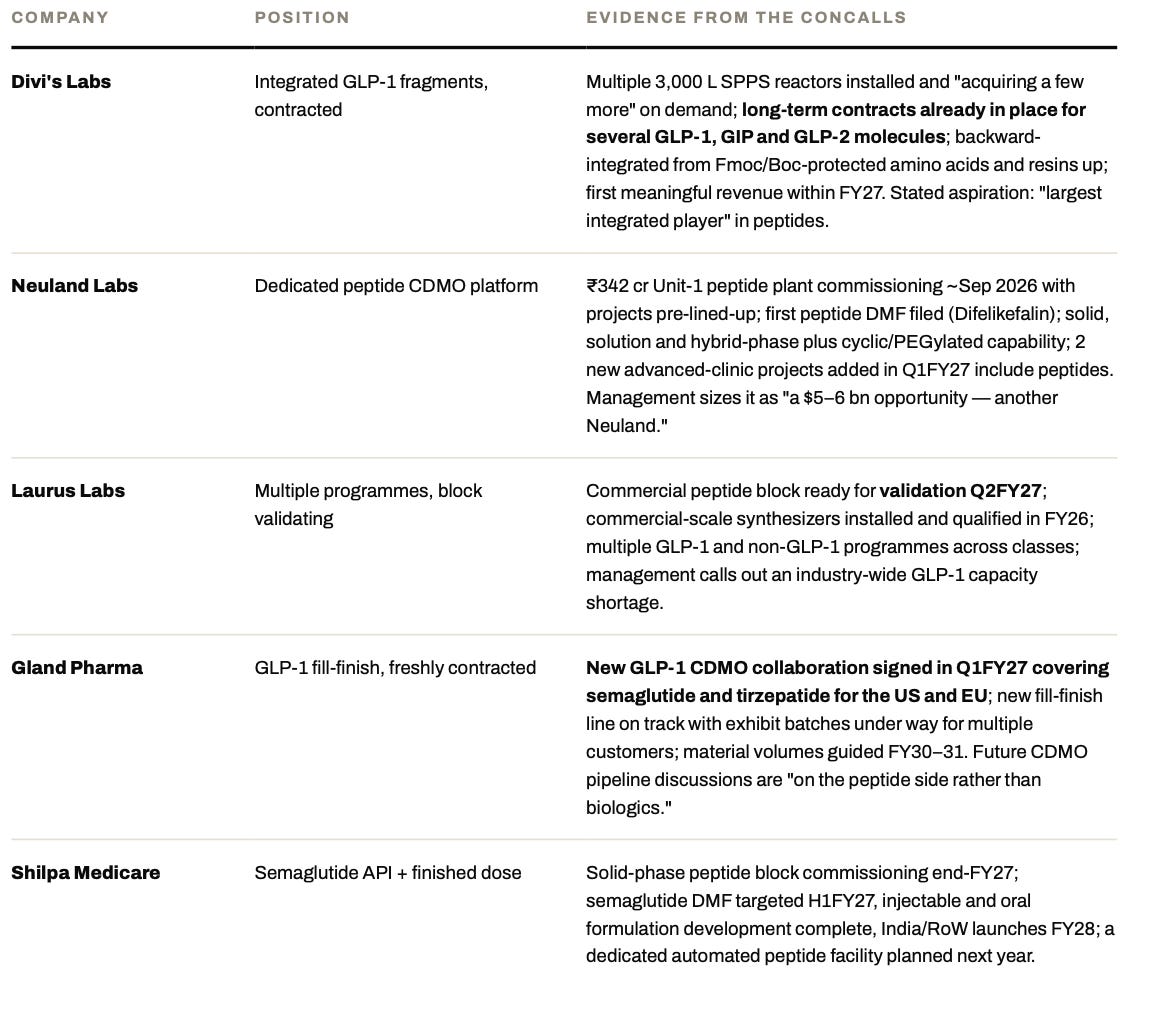
Rung 3 — Building the capability, revenue later
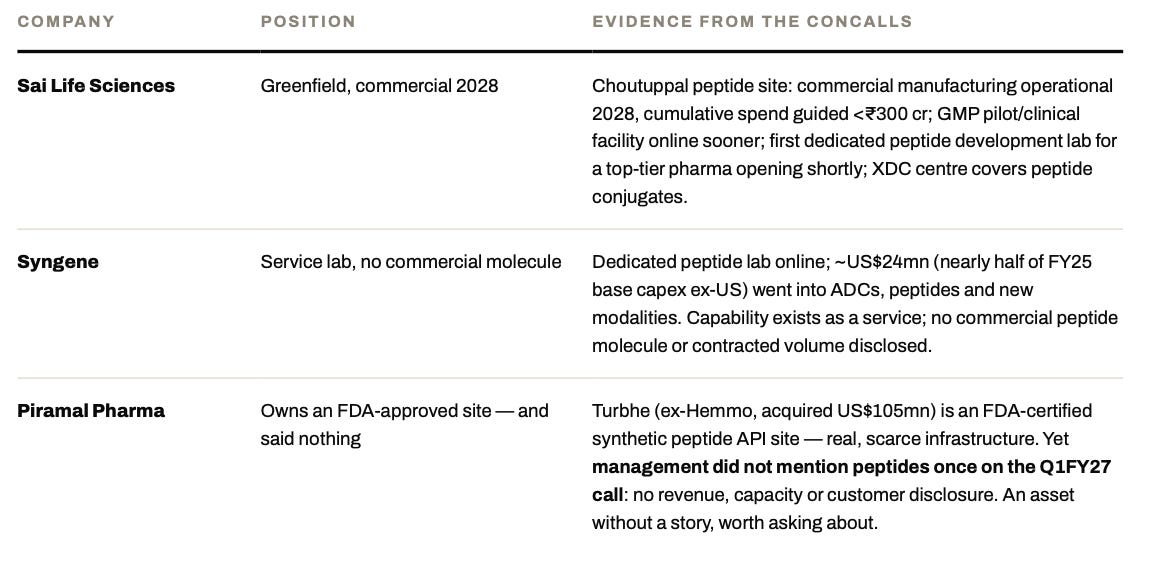
Rung 4 — R&D, Fragments or Intent only
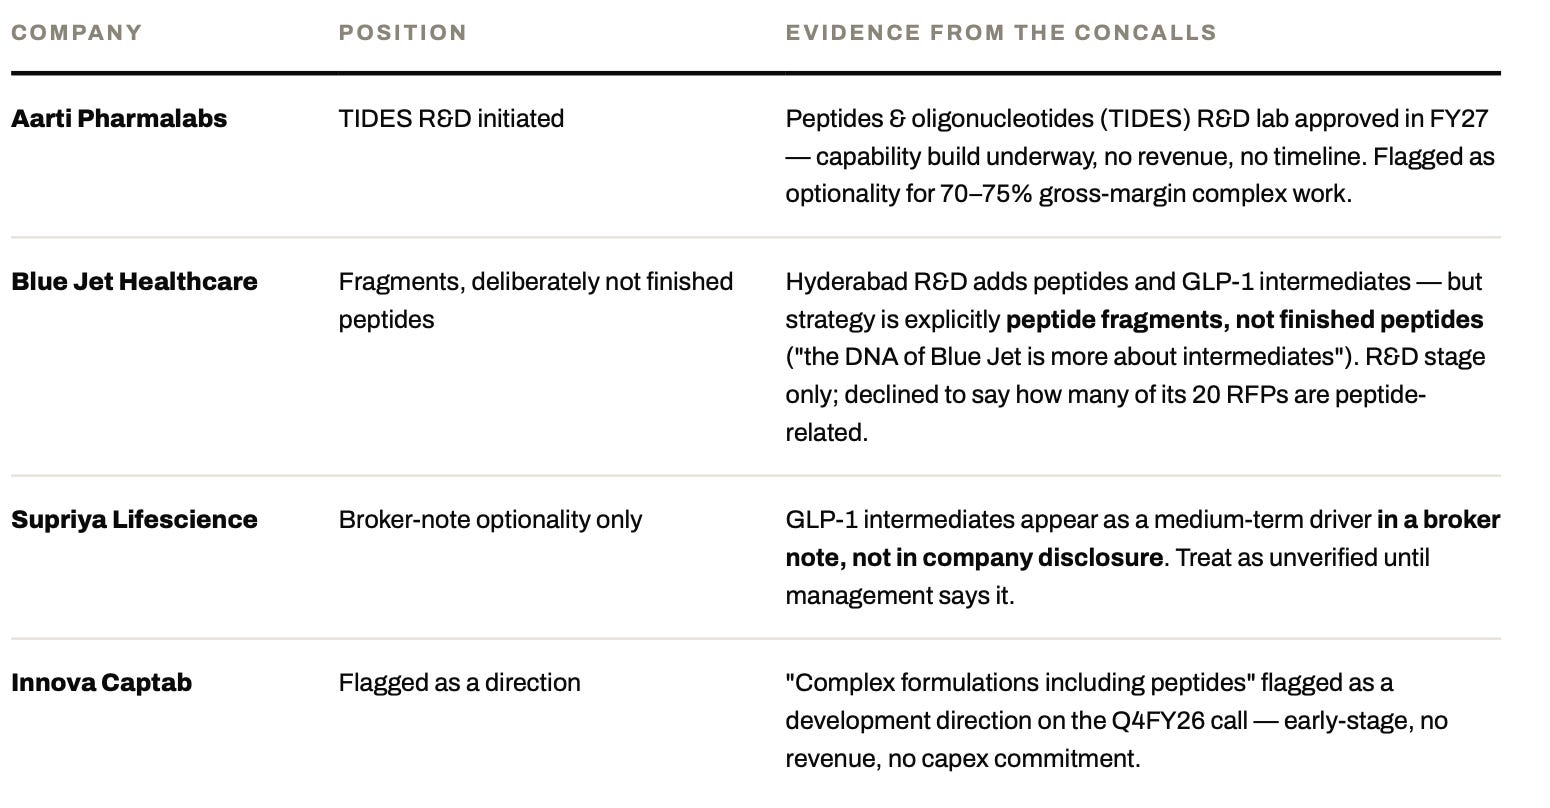
Rung 5 — No peptide exposure (and that is a finding)
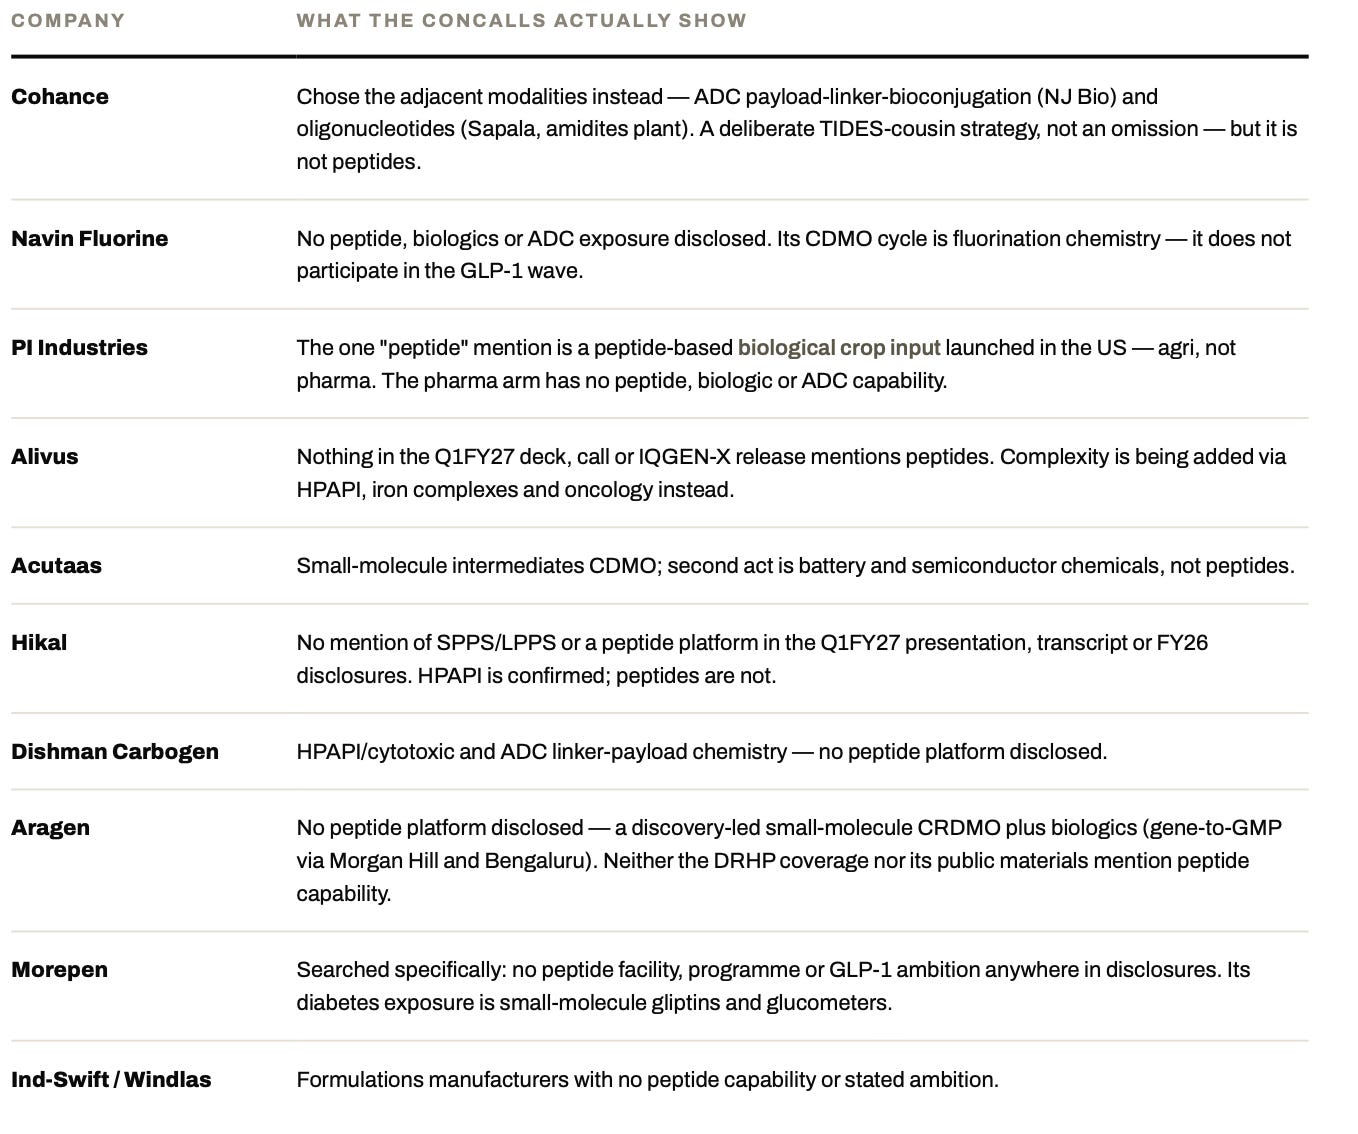
Fifteen of twenty-six companies have some claim on the word “peptide”. Three earn real revenue from it today. The gap between those two numbers is where the diligence lives.
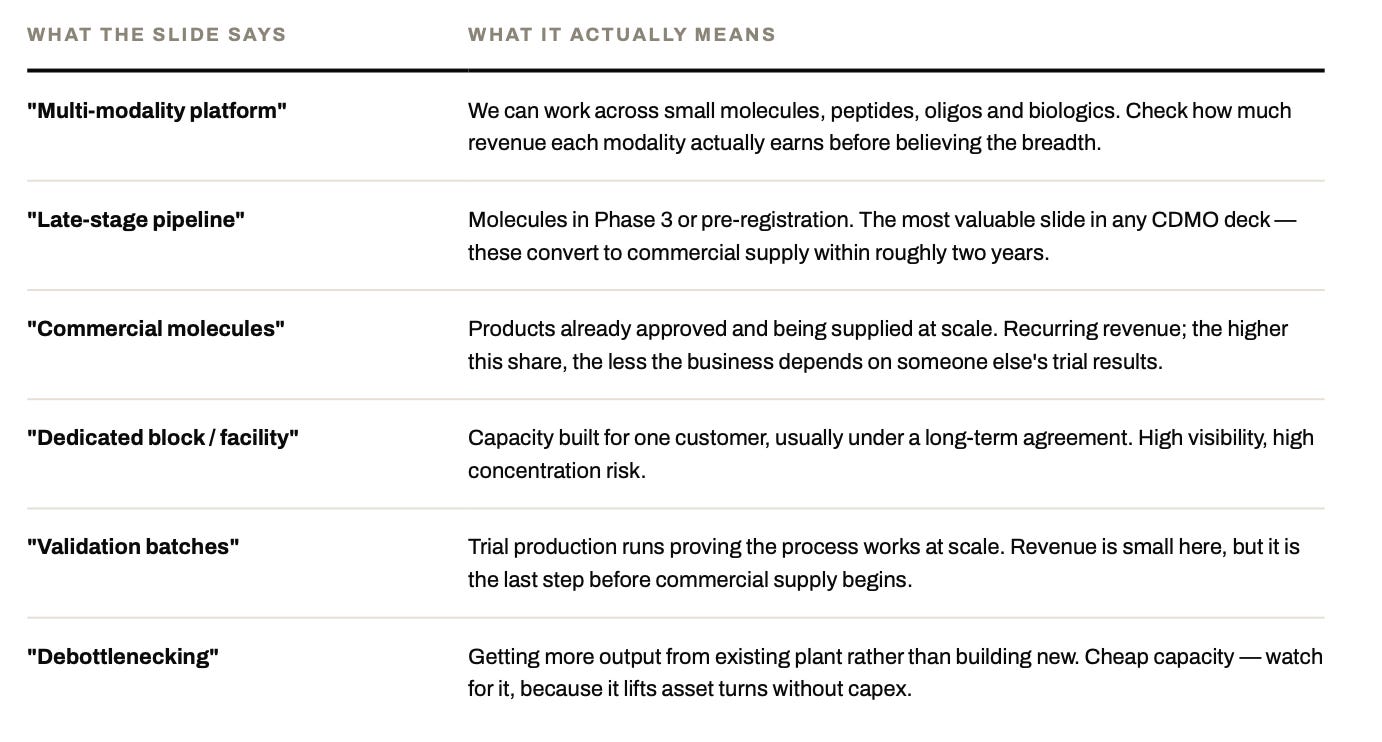
The deck decoder
A translation table for the phrases that recur in almost every CDMO presentation.
GLOSSARY
The terms that appear on every second slide. Each one includes what it means and, more usefully, what it tells you as an investor.
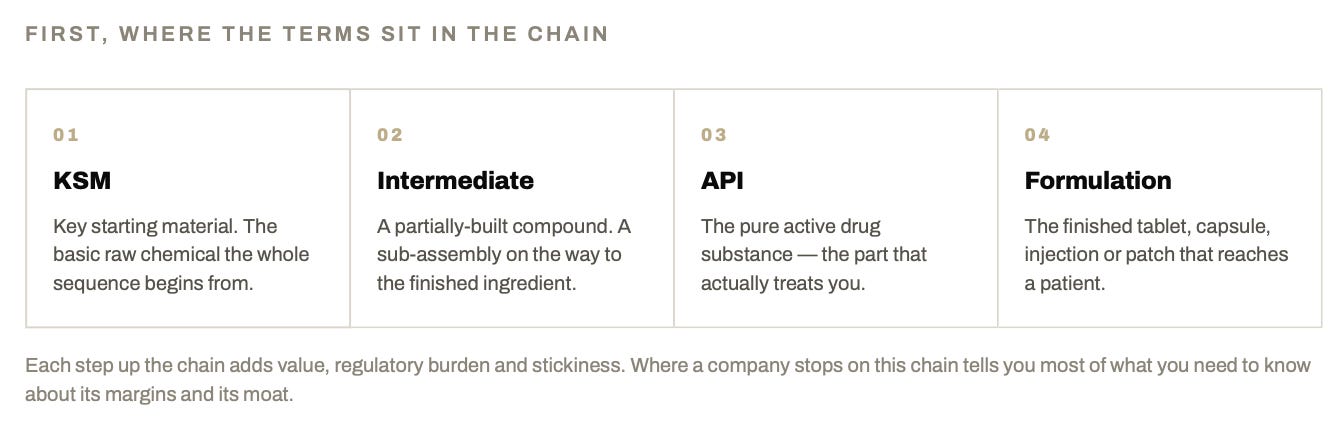
Intermediate - CHEMICAL SUB-ASSEMBLY
A partially-built chemical compound — not yet the finished drug ingredient, but a necessary stepping stone. Raw chemicals get reacted through several stages to build intermediates; a few final reactions then convert an intermediate into the API.
What it signals: intermediate suppliers sit furthest from the patient. Lower value per kg, but also lower regulatory exposure — and a supplier that never competes with its own customer, which is itself a selling point.
API - ACTIVE PHARMACEUTICAL INGREDIENT
The actual drug substance is the pure chemical that produces the medicinal effect. It is what’s inside the pill, not the pill itself. A company making “Apixaban API” manufactures the pure blood-thinning compound and sells it to whoever turns it into tablets.
What it signals: the core of most Indian CDMO businesses. Requires regulatory filings and inspected facilities, which is precisely what makes it defensible.
Biologics LARGE MOLECULES
Drugs grown using living cells rather than synthesised in a reactor antibodies, vaccines, insulin, and other large complex molecules. They generally need cold-chain handling and cannot be copied exactly, which is why their copies are called biosimilars rather than generics.
What it signals: capital-heavy and slow to qualify, but far stickier once won. Watch utilisation carefully because idle bioreactor capacity is one of the most expensive mistakes in this industry.
Peptides - THE MIDDLE GROUND
Short chains of 2–50 amino acids, chemically synthesised (usually via SPPS) rather than grown in cells which are larger and more complex than typical small molecules, but not full biologics. GLP-1 drugs like semaglutide belong here.
What it signals: today’s hottest CDMO growth segment. The differentiator is not who can make peptides, but who has commercial-scale blocks with contracted volumes behind them.
NCE - NEW CHEMICAL ENTITY
A molecule never before approved as a drug which is genuinely new chemistry, discovered by an innovator over years and billions of dollars. When a CDMO reports “NCE projects,” it is manufacturing patented, still-developing or newly-launched molecules for those innovators.
What it signals: high value and long contracts, but the revenue is hostage to someone else’s clinical trial. A Phase 2 failure can erase a project which is why the stage mix of an NCE pipeline matters more than its headline count.
NBE - NEW BIOLOGICAL ENTITY
The biologic equivalent of an NCE, a novel large molecule (typically an antibody or protein therapeutic) that has never been approved before.
What it signals: the same innovator-linked economics as an NCE, but with biologics timelines and capital intensity attached.
ANDA - ABBREVIATED NEW DRUG APPLICATION
The US FDA filing used to seek approval for a generic drug. “Abbreviated” because the applicant doesn’t repeat the full clinical trial programme and it only has to prove its version is bioequivalent to the original.
What it signals: ANDA counts are a proxy for a company’s shots on goal in the US generics market. Read them with care: filings ≠ approvals ≠ launches ≠ profits, and a large ANDA book in eroding categories can flatter a story that isn’t earning.
NDA / 505(b)(2) - NEW DRUG APPLICATION
The full FDA filing for a genuinely new drug, backed by complete clinical data. The 505(b)(2) route sits in between: a new version of something already approved :- a new dose, formulation or delivery route relying partly on the original’s data.
What it signals: 505(b)(2) products carry far better margins than plain generics with a fraction of the cost of a true NDA. When an Indian company highlights them, it is telling you it is climbing the value ladder.
DMF - DRUG MASTER FILE
A confidential dossier filed with a regulator describing exactly how an API or intermediate is made and controlled. Customers reference it in their own applications without ever seeing the contents.
What it signals: DMF count is a rough gauge of API breadth and regulatory maturity. Filing one is also how a supplier gets designed into a customer’s product which is what makes the relationship hard to unwind. The European equivalent is a CEP.
Near term groth driver supriya
Anesthetics
Cardiovascular
ADHD products
DSM contracts (Vitamins)
GLP-1 not growth driver
SOIC student.
Thank you team, it has summarised many complex thing from pharma and how to evaluate value chain